
Blogs
The world of Pokemon TCG Pocket is filled with different deck styles, and Dragalge ex Decks offer an exciting option for players who enjoy strategic battles. Instead of relying only on fast attacks, Dragalge ex focuses on careful preparation, smart resource usage, and creating advantages over multiple turns. Trainers who want to build effective strategies can explore different Pokemon TCG Pocket Cards to develop a complete deck that supports Dragalge ex and improves performance against various opponents.
A successful Dragalge ex Deck is built around balance. Players need to combine offensive power with consistency, ensuring that the deck can perform well throughout the entire match. While Dragalge ex serves as the main attacker, the supporting cards determine how effectively the deck can survive difficult situations and maintain control of the battlefield.
The Role of Dragalge ex in Pokemon TCG Pocket
Dragalge ex provides players with a unique approach to competitive battles. Many popular decks focus on overwhelming opponents quickly, but Dragalge ex rewards a more calculated playstyle. It allows trainers to create pressure while maintaining enough resources for future turns.
The biggest advantage of this strategy is flexibility. Depending on the opponent’s deck, Dragalge ex users can adjust their approach. Some matches may require a defensive strategy, while others may provide opportunities for aggressive plays.
Understanding the strengths and limitations of Dragalge ex is essential. Although it can become a powerful attacker, it still depends on proper support and timing. Players who rush without preparation may find themselves struggling later in the match.
Building a Reliable Dragalge ex Deck
When creating a Dragalge ex Deck, consistency should always be a priority. A strong deck should have enough options to access important cards while avoiding unnecessary additions that reduce efficiency.
The main focus should be supporting Dragalge ex throughout the battle. Cards that help with searching, drawing, or managing resources can improve the deck’s overall performance. These tools allow players to set up faster and respond more effectively to different threats.
Backup attackers are also valuable additions. While Dragalge ex is the centerpiece, competitive matches can change quickly. Having alternative options prevents opponents from gaining an easy advantage by targeting one specific Pokemon.
Energy management is another major factor. Players must carefully consider how much energy the deck needs and how efficiently it can use those resources. A well-balanced energy setup ensures Dragalge ex can attack when necessary without slowing down the rest of the strategy.
Advanced Gameplay Tips for Dragalge ex Users
One of the most important skills for Dragalge ex players is recognizing the correct moment to make aggressive moves. Good players understand that every action should contribute to their overall strategy.
During the early stages of a match, setting up the board is usually more important than dealing immediate damage. Building a strong position creates more opportunities in later turns and reduces the chance of losing momentum.
Mid-game decisions often determine victory. Players should analyze the opponent’s available options and choose actions that create the most pressure. Sometimes delaying an attack can lead to a much stronger position.
Another important skill is adapting to different opponents. Every deck has unique strengths and weaknesses. A strategy that works against one opponent may fail against another. Successful Dragalge ex trainers constantly adjust their decisions based on the situation.
Improving Your Collection and Deck Options
As Pokemon TCG Pocket continues to grow, new cards and strategies will continue changing the competitive environment. Players who want to keep their Dragalge ex Deck competitive should regularly experiment with different builds.
Trying new combinations can reveal powerful strategies that are not immediately obvious. Testing different support cards and analyzing battle results are excellent ways to improve both deck quality and personal skill.
Having access to a wider collection also makes experimentation easier. Players who want to expand their deck-building possibilities can choose to cheap Pokemon TCG Pocket Cards and explore additional options for improving their Dragalge ex strategy. With thoughtful preparation, strong card choices, and effective decision-making, Dragalge ex Decks can become a reliable choice for trainers looking for a unique competitive experience.
PW Consulting: Worldwide Conductive Acetylene Black for Li‑ion Battery Market Poised to Expand at 11.45% CAGR, Signaling Rapid Global Growth
By pmarketresearch, 2026-08-18
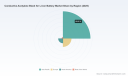
Worldwide Conductive Acetylene Black for Li‑ion Battery Market — Strategic Outlook 2026
PW Consulting today publishes an executive industry brief accompanying our full market study, Worldwide Conductive Acetylene Black for Li‑ion Battery Market. This briefing distills the report’s most consequential, decision‑critical insights for corporate leaders, procurement teams, and investors preparing to make strategic moves in 2026. It demonstrates why conductive acetylene black is no longer a niche commodity but a strategic raw material whose supply, technology pathway, and carbon profile will materially influence battery competitiveness and downstream cost and performance curves.
Worldwide Hot Melt Adhesive Film Market
Market snapshot: momentum and scale
Our model shows the market for conductive acetylene black used in lithium‑ion batteries expanding rapidly through the decade. From a measured market base in 2020, the market reached a robust global size in 2025 and our forecast projects sustained acceleration from 2026 through 2032 at a compound annual growth rate (CAGR) of approximately 11.45%. Under PW Consulting’s central scenario, the market value rises materially by 2032, reflecting combined demand growth from electric vehicles, portable electronics, and grid‑scale storage as well as ongoing performance and purity upgrades required by advanced electrode formulations.
Worldwide Sample Evaporator Market
Why acetylene black matters now
- Conductive additives are a small share of cell mass but an outsized driver of power delivery, cycle life, and electrode manufacturability. Acetylene black’s morphology and ultra‑low metallic impurity profile make it a preferred choice for high‑performance LIB anode and cathode formulations.
- As battery makers chase higher energy density and faster charging rates, the tolerance for impurity and inconsistency shrinks. That raises the bar for battery‑grade carbons and converts what was once a commodity buy into a strategic sourcing decision.
- Concurrently, decarbonization of upstream carbon production and secure access to acetylene feedstock are emerging as procurement KPIs. Buyers increasingly evaluate not just price and quality, but the carbon intensity and contractual integrity of supply chains.
Primary market dynamics shaping 2026 decisions
- Capacity additions and timing. Significant greenfield capacity expansions are scheduled to come online in the 2026 window. These additions will alter regional flows and bargaining parameters for large offtakers; understanding precise commissioning schedules and ramp profiles is a procurement imperative.
- Feedstock dependency. Acetylene black production remains dependent on acetylene feedstocks, historically sourced via calcium carbide or newer low‑carbon plasma methods. Feedstock sourcing agreements and proximity to acetylene suppliers materially impact unit economics and risk exposure.
- Policy and financing. Public finance and subsidies are already shaping the competitive landscape: government‑backed loans and technology subsidies are accelerating low‑carbon acetylene programs and incentivizing near‑site manufacturing. These measures will influence siting decisions and long‑term cost curves.
- Concentration and supplier power. The market exhibits moderate to high concentration among leading manufacturers. A small set of established producers account for the majority of battery‑grade acetylene black capacity, which creates both stability in quality standards and potential bottlenecks for rapid demand spikes.
- Technology and product differentiation. Suppliers are competing on ultra‑low impurity grades, morphology control, and tailored electrolyte‑electrode interaction properties. The winners will be those who combine consistent product specs with transparent low‑carbon production pathways.
Competitive landscape: what to watch in 2026
Our report profiles incumbent and emerging suppliers and maps strategic moves that will determine supply availability and pricing dynamics in 2026. Key vendor developments through 2025 highlight concrete shifts:
Worldwide Retail LMS Software Market
- Denka Company Limited (Tokyo, Japan) continues to promote ultra‑pure product formulations optimized for next‑generation batteries, while pursuing capacity diversification through international joint ventures. Denka’s supported initiatives—including public financial arrangements and technology subsidies for low‑carbon acetylene—demonstrate how industrial policy and corporate strategy can coalesce to secure prioritized feedstock and accelerated production capability.
- Orion Engineered Carbons (Luxembourg, with major operations in Europe and the USA) is scaling capacity with a new dedicated acetylene black plant in La Porte, Texas. Commissioning anticipated in 2026 will materially expand effective battery‑grade capacity available to North American and global OEMs and should be closely watched by buyers seeking to rebalance regional exposure.
- IRPC (Thailand) and other regional producers are positioning premium grades for battery use, reinforcing Asia’s role in both manufacturing and innovation. Regional manufacturing footprints remain a strategic lever for cellmakers seeking to shorten supply chains.
- U.S. suppliers such as Soltex Inc. continue to supply a diversified portfolio of grades, enabling specialized applications and fast prototyping cycles for battery developers.
Collectively, the top three and five producers capture a majority share of the market, underscoring structural supplier influence. This concentration creates both opportunities for long‑term partnerships and negotiation leverage for large offtakers—and systemic risk if demand accelerates beyond planned expansions.
Strategic actions for 2026—operational and commercial playbook
Leaders preparing 2026 budgets and sourcing strategies should treat conductive acetylene black as a strategic procurement category. Our report extracts practical tactics from market data and supplier interviews; below are the highest‑impact actions we recommend:
- Segmentation of sourcing strategies: separate high‑purity, low‑carbon grades for critical cell lines from broader commodity buys for legacy products. Tailor contract length and flexibility accordingly.
- Secure upstream visibility: negotiate early access to feedstock arrangements or second‑tier supply to mitigate acetylene supply shocks. Consider feedstock‑to‑product joint ventures for critical capacity.
- Lock in conditional offtakes around commissioning milestones: as new facilities come online in 2026, staggered offtake contracts tied to ramp rates can be more cost‑effective than spot exposure.
- Implement supplier scorecards that weight carbon intensity and traceability alongside quality and price. Regulatory and customer scrutiny of embodied emissions will grow, affecting procurement KPIs.
- Stress‑test sourcing strategies under multiple growth scenarios. Rapid EV adoption, accelerated ESS deployment, or a slower‑than‑expected scale of low‑carbon feedstock can each produce divergent outcomes; prepare contingency plans for inventory, logistics, and contract flexibility.
- Pursue collaborative R&D and qualification programs to accelerate adoption of next‑gen acetylene black grades, shortening qualification cycles and locking in technical differentiation that is difficult for competitors to replicate quickly.
What the full PW Consulting report contains (practical deliverables)
The full report is designed as an operational manual for 2026 decision‑making. Key deliverables include:
- Granular, vendor‑level profiles and benchmarking across manufacturing footprint, product grades, QA practices, and supply chain resilience metrics.
- Detailed market forecasts and scenario models (2026–2032) reflecting alternative EV/ESS growth paths and technology adoption curves, with sensitivity to feedstock and policy interventions.
- Supply map and capacity‑commissioning calendar, highlighting where and when new production will materially change regional flows and negotiating leverage.
- Manufacturing cost models and margin drivers for acetylene black production under prevailing feedstock configurations, including low‑carbon process variants.
- Commercial playbook templates—offtake term structures, price indexation mechanisms, quality acceptance criteria, and escalation clauses to operationalize strategic sourcing choices.
- M&A and investment heatmaps identifying potential acquisition targets, JV partners, and white‑space investment opportunities for industrial players and private equity.
- Regulatory and policy tracker that evolves with subsidy programs, public financing instruments, and technology grants influencing low‑carbon acetylene adoption.
To respect the “trailer” principle, this briefing intentionally highlights scope and strategic takeaways while withholding the full set of subsegment tables and supplier‑level commercial datapoints that appear exclusively in the complete report package.
Implications for investors, OEMs, and battery manufacturers
2026 will be a decision point: organizations that align procurement, engineering, and corporate strategy to the emerging geometry of acetylene black supply and low‑carbon production will gain first‑mover advantages in cost, quality, and sustainability narratives. Investors should prioritize companies with transparent feedstock strategies and credible commissioning schedules. OEMs and cellmakers should convert short‑term contingency planning into multi‑year supplier partnerships that embed ramp commitments and technology co‑development clauses.
Next steps
PW Consulting’s full Worldwide Conductive Acetylene Black for Li‑ion Battery Market report provides the proprietary datasets, vendor scorecards, and commercial templates needed to operationalize the strategies summarized here. For procurement teams, engineering groups, and corporate strategists planning for 2026 and beyond, the report is a tactical roadmap—complete with executable playbooks and scenario models—that transforms market intelligence into immediate action.
Contact PW Consulting or visit our report page to access the full analysis, obtain tailored briefings for your executive committee, or license the underlying datasets and supplier models to support 2026 planning and contract negotiations.
For detailed analysis of this topic, please visit the official page: Worldwide Conductive Acetylene Black for Li-ion Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Industrial Burden Carrier Market Poised for Expansion — Forecasted 4.95% CAGR Signals New Strategic Opportunities
By pmarketresearch, 2026-08-18
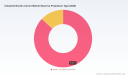
Worldwide Industrial Burden Carrier Market — Strategic Imperatives for 2026
Executive snapshot
The Worldwide Industrial Burden Carrier Market has moved from a niche operational asset to a strategic fleet component across manufacturing, logistics, aviation and heavy industry. Our latest analysis at PW Consulting shows that the market expanded from USD 420.5 Million in 2020 to USD 535.4 Million in 2025 (base year). Under our modeled scenarios the sector is projected to continue its steady climb into the early 2030s — with a 2026 projection of USD 552.9 Million and a trajectory that reaches USD 750.85 Million by 2032, reflecting a compound annual growth rate (CAGR) of 4.95% across the forecast period.
eSIM Module Market
Why this report matters for 2026 decision-making
-
Timing: 2026 is the inflection year for many operators evaluating fleet electrification, modular platforms and lifecycle service monetization. The numbers above show sustained market expansion, but the strategic opportunity lies in timing investments to capture efficiency gains and regulatory tailwinds.
Worldwide Blogger Outreach Software Market -
Regulatory drivers: Global zero-emission mandates, indoor air-quality standards and evolving safety norms (including ongoing relevance of ISO 3691-1 for related self-propelled industrial trucks) are accelerating the shift toward electric and low-emission burden carriers. These mandates change procurement specifications, total-cost-of-ownership (TCO) calculations and upgrade cycles.
Worldwide Swim Club Management Software Market -
Supply-chain and input-cost sensitivity: Steel and related raw-material price fluctuations — from iron ore through hot-rolled coil (HRC) — materially affect chassis and frame economics. Procurement strategies that lock favorable terms or enable material substitutes de-risk manufacturing margins.
-
Operational dynamics: Persistent labor shortages and the rise of warehouse automation are increasing reliance on burden carriers to maintain throughput, reduce manual handling injuries, and integrate with warehouse management systems (WMS) and fleet telematics.
What the PW Consulting report contains — practical, decision-ready content
-
Executive summary with rapid-read strategic implications for C-suite, procurement and plant operations teams.
-
Market-sizing and three-scenario forecasting (baseline, upside, downside) anchored to our 2025 base and extending through 2032, including sensitivity tests on raw-material prices, battery-cost curves, and regulatory adoption timelines.
-
Buyers’ playbook — procurement checklists, supplier evaluation templates, and acquisition vs. lease TCO calculators calibrated for burden carriers.
-
Supply-chain heatmap — supplier concentration, single-sourcing risks, and tactical hedging strategies for steel and battery cell exposure.
-
Product and technology roadmap — feature-priority matrices (battery chemistry, modular chassis, telematics), integration pathways to WMS and AMR systems, and upgradeability guidelines to protect installed-asset value.
-
Commercial models — pricing tiers, service-contract designs, extended-warranty economics and aftermarket parts strategies to monetize installed fleets.
-
M&A and partnership screening — criteria-driven shortlist of targets, valuation frameworks and integration playbooks for scale or capability acquisitions.
-
Country- and facility-level implementation playbooks — compliance checklists, CAPEX phasing, and change-management templates for frontline adoption.
Competitive landscape — what leading vendors are signaling
The sector is populated by diverse OEMs ranging from specialist burden-carrier manufacturers to large material-handling conglomerates. The competitive picture is best described as evolution toward electrified, configurable platforms and service-led differentiation. Below we summarize the strategic posture of key players covered in the report.
-
Motrec International Inc. (Quebec, Canada) — https://motrec.com/
Strengths: Highly configurable electric flatbed designs and proven heavy-load platforms. Strategic angle: customization and heavy-duty reliability. Implication: Motrec is well-positioned to win bespoke fleet deployments where payload and durability outweigh unit-price sensitivity. -
Taylor-Dunn Manufacturing Company (Anaheim, CA, USA) — https://www.taylor-dunn.com/
Strengths: Broad portfolio with proven utility in tight-pathway environments and high-towing variants. Strategic angle: ergonomics and operational familiarity. Recent activity: launched new ergonomics-focused product line in 2025 to address operator comfort and safety, supporting longer duty cycles. -
Cushman (Textron Specialized Vehicles) (Augusta, GA, USA) — https://cushman.txtsv.com/
Strengths: Brand scale, dealer networks and product breadth across personnel and material movement. Strategic angle: channel depth and integrated aftermarket offerings. Implication: Cushman competes on total ecosystem rather than single-model advantages. -
Pack Mule (Capacity Trucks) (USA) — https://packmule.com/
Strengths: Heavy-duty NXG and ALPHA series engineered for manufacturing and distribution centers. Strategic angle: payload and towing as differentiators for industrial customers facing high throughput demands. -
Johnson Industries Inc. (Kentucky, USA) — https://johnsonindustries.com/
Strengths: Safety-first designs tailored for mining and heavy industry. Strategic angle: ruggedization and compliance with demanding safety protocols. -
Trowin Industries (USA) — https://www.trowin.com/
Strengths: Versatile flatbed platforms for maintenance, rescue and baggage handling. Strategic angle: role-specific versatility. -
Columbia ParCar Corp (Reedsburg, WI, USA) — https://www.columbiaparcar.com/
Strengths: Broad product family focused on industrial material and personnel movement. Strategic angle: value-oriented platforms with aftermarket support. -
Bobcat Company (West Fargo, ND, USA) — https://www.bobcat.com/
Strengths: Leveraging construction-equipment engineering to deliver heavy-capacity carrier models. Recent activity: announced enhanced warehouse-capability model availability in early 2026, signaling continuity of product refresh cadence and channel readiness. -
Toyota Material Handling (Columbus, IN, USA) — https://www.toyotaforklift.com/
Strengths: End-to-end material handling portfolio and extensive dealership network. Strategic angle: integration with forklifts, automation systems and fleet services. -
HC Forklift America (USA)
Strengths: Newer entrants focusing on lithium-ion propulsion and multi-seater/enclosed cabin options. Recent activity: showcased a lithium-ion, 4-seater model with enclosed cabin at a major trade show in March 2026 — an example of differentiation through cabinization and battery chemistry.
Recent strategic signals and what they mean
-
Product refreshes and trade-show debuts in 2025–2026 demonstrate that vendors are racing to lock design wins with electrified, operator-centric features rather than competing solely on base-platform price.
-
OEMs are layering aftermarket and telematics services to build recurring revenue streams — an important consideration for buyers that want predictable lifecycle costs.
-
New lithium-ion offerings and enclosed-cabin variants suggest that vendors are anticipating use-cases beyond traditional warehouse floors — including airport operations, campus mobility and controlled-environment manufacturing.
Five priority moves for 2026
-
Accelerate pilot-to-scale electrification: Run segmented pilots that validate battery chemistry, duty-cycle matching and charging infrastructure — consolidate learnings into a 24–36 month roll-out plan tied to TCO thresholds.
-
Hedge raw-material exposure: Negotiate multi-year supply agreements or volume options with steel and battery suppliers; explore alternative materials and modular subframes to reduce margin volatility.
-
Design for service revenue: Structure aftermarket contracts (parts, predictive maintenance, remote diagnostics) and align incentives with dealers for uptime guarantees; this improves ROI on higher-spec electric platforms.
-
Prioritize integration and safety compliance: Ensure new fleet specifications include telematics for WMS/ERP integration and meet or exceed applicable safety standards; this reduces friction during deployment and protects operating metrics.
-
Targeted M&A or partnership play: For OEMs and Tier-1 suppliers, evaluate bolt-on acquisitions that add battery expertise, telematics platforms or dealer networks. For large end-users, consider strategic partnerships for shared charging or fleet-as-a-service arrangements.
How to use this research in your 2026 planning cycle
Executives should treat the report as both a market map and an implementation manual. Use the forecast scenarios to stress-test your procurement calendar and CAPEX approvals; use the supplier heatmap and raw-material sensitivity analyses to build procurement contingencies; and use the buyer-playbook sections to align internal stakeholders on preferred-spec frameworks and service-level KPIs.
Next steps and where to access the full intelligence
PW Consulting’s Worldwide Industrial Burden Carrier Market report is designed to be executable for teams setting strategy in 2026. This article provides the strategic context and executive actions; the full report contains the granular segmentation, region- and application-level forecasting, competitive share tables, and downloadable financial models that underpin our recommendations. For license options, bespoke advisory, and access to the datasets and software models that drive our forecasts, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Burden Carrier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Stainless Steel Vacuum Flask Market to Rise from USD 5,620M in 2025 to USD 8,035M by 2032 at a 5.24% CAGR, Led by Asia‑Pacific
By pmarketresearch, 2026-08-18
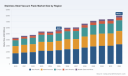
Worldwide Stainless Steel Vacuum Flask Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s latest market research, prepared with a 2025 base and a 2026–2032 forecast horizon, distils the competitive, commercial, and supply‑chain dynamics that will determine winners and losers in the stainless steel vacuum flask industry over the next seven years. Our proprietary market model projects continued expansion from a multi‑billion USD market in 2025 toward a materially larger global opportunity by 2032, underpinned by a steady compound annual growth rate of 5.24%. For commercial leaders preparing budgets, capex plans, product roadmaps, M&A pipelines and retail negotiations in 2026, this report translates headline growth into actionable choices.
Worldwide Organic Detox Tea Market
Why this briefing matters for 2026 strategy
-
Growth with disruption: A predictable mid-single‑digit CAGR masks multiple near‑term shocks — raw material inflation, product safety incidents and a shifting retail mix. Leaders must reconcile steady top‑line expansion with episodic margin and reputational risks.
Worldwide Mechanical Presses Machine Market -
Fragmented supply economics: The market’s relatively low concentration (CR3 ≈ 18.45%, CR5 ≈ 26.32%) signals buyer power opportunities and M&A upside, but also implies intense competition on price and distribution. Strategic players will need distinct differentiation or scale plays to expand margin pools.
Worldwide Oil Cooling Units Market -
Operational levers are decisive in 2026: Decisions on dual‑sourcing, inventory posture, raw‑material hedging, and testing protocols will materially affect P&L and time‑to‑shelf across the year.
-
Channel and premiumization are not binary choices: High‑growth pockets remain in premium, lifestyle and sustainability‑led segments while e‑commerce and omnichannel strategies reallocate distribution economics. 2026 will be a year of calibration rather than wholesale reinvention.
What’s inside the full PW Consulting report (practical, executive‑ready)
-
Forward‑looking market model with scenario outputs: baseline, stress (raw‑material shock), and acceleration (premiumization surge) — all linked to revenue, margin and inventory outcomes for 2026–2032.
-
Channel playbooks: tailored go‑to‑market templates for D2C, online retail, supermarkets/hypermarkets and specialty channels with margin levers, promotional cadence, and SKU rationalization guidance.
-
Supply‑chain heatmaps and supplier scorecards: manufacturability, capacity, quality history and on‑shore/off‑shore risk scoring to prioritize dual‑sourcing and contingency stock policies.
-
Cost‑pass through and pricing toolkit: elasticity testing frameworks and recommended price architecture to protect margins when stainless steel and nickel costs move.
-
Regulatory and safety readiness checklist: recalls and product‑safety playbooks, including incident response, communication templates, and third‑party testing protocols.
-
M&A and portfolio playbook: target typologies, valuation approaches, integration risks, and a short list of acquisition templates aligned with scale, premium, or capability buys.
-
Innovation and sustainability roadmap: materials tradeoffs (304 vs 316 stainless decisions), recyclability claims verification, and consumer‑facing sustainability narratives that convert into price premium analytics.
Competitive landscape — strategic implications for 2026
The sector combines household consumer brands, premium lifestyle players, and high‑volume OEM/ODM manufacturers. Below we synthesise the competitive positions that matter for 2026 planning.
-
Thermos (China / US) — Market leadership and brand franchise provide shelf dominance and retail leverage. However, recent product‑safety incidents involving millions of units have elevated regulatory scrutiny, warranty and recall risk, and downstream liability exposure for retailers and distributors. For strategy teams, the priority is to stress‑test quality assurance, supplier traceability and crisis communications protocols.
-
Zhejiang Haers and other large Chinese OEMs — These suppliers offer scale, cost competitiveness and strong ODM/OEM capabilities to hundreds of brands. Their strengths make them natural partners for private label and volume playbooks, but exposure to commodity cycles and export regulation necessitates robust procurement and contractual protections.
-
Tiger & Zojirushi (Japan) — Premium engineering, reputation for durable thermal performance, and a customer base that values reliability support resilient margins. Their playbook is quality‑led product differentiation, which is attractive to acquirers seeking margin resilience in a crowded market.
-
Hydro Flask, Klean Kanteen, YETI (United States) — Lifestyle and sustainability credentials drive premium pricing and brand loyalty. These players illustrate the value of community, design and environmental positioning in extracting higher unit economics.
-
Regional OEMs and smaller manufacturers (e.g., Steel Termos, Mountop, LAIKOE) — Important for regional distribution and bespoke product lines. They will be focal points for consolidation and fast capacity augmentation if demand surprises on the upside.
Collectively, these dynamics create a market where brand equity, manufacturing depth, and channel mastery coexist — but where no single player exerts dominant pricing power. That creates persistent opportunities for acquisition, private label growth, and vertical integration in 2026.
Key external risks and industry signals to monitor
-
Commodity volatility: Recent material cost inflation is pressuring margins. A sustained upward move in stainless steel or nickel will force either margin compression or elevated retail price increases; both outcomes require different tactical responses.
-
Product‑safety and regulatory scrutiny: High‑profile recalls accelerate retailer due‑diligence and increase insurance costs. Firms without rapid traceability and third‑party testing frameworks will face longer lead times for listings and higher compliance costs.
-
Trade and concentration risks: Current global manufacturing concentration creates vulnerability to geopolitical or logistics shocks. Diversification of manufacturing footprint, or contractual assurances with key suppliers, should be prioritized.
-
Channel shifts: Consumers continue shifting toward online and specialty lifestyle channels. Retailers and brands that optimize digital funnels, subscription models and premium channel experiences will capture disproportionate share of growth.
Practical 90‑day actions for executives planning 2026
-
Initiate a supplier stress‑test: map second‑tier suppliers, validate alternative sourcing, and lock short‑term hedges for critical metals where feasible.
-
Run a SKU profitability audit: identify low‑margin SKUs to rationalize and reallocate shelf / digital real estate to high‑return products.
-
Implement a recall readiness simulation with legal, quality and comms teams; ensure insurance and liability clauses are current.
-
Fast‑track premium lane pilots: test higher‑margin SKUs with differentiated finishes, warranty offers, and sustainability credentials via direct channels.
-
Evaluate strategic M&A targets: prioritize bolt‑on OEMs for capacity and regional reach, or niche premium brands to accelerate margin expansion.
How PW Consulting supports boardroom decisions in 2026
Beyond the published market study, PW Consulting offers executive workshops that translate the report’s scenario outputs into boardroom‑ready decisions: bespoke revenue and cost models, target screening for strategic acquisition, supplier renegotiation playbooks, and a regulatory‑compliance checklist tailored to your SKUs and geographies. Our deliverables are designed to move from insight to implementation within 60–90 days.
The full report contains the granular segmentation, SKU‑level proxies, channel elasticities and the proprietary heatmaps that clients use to quantify opportunity and risk. We intentionally omit those core subsegment tables from this preview to preserve the usable intelligence that guides tactical 2026 moves.
To obtain the full Worldwide Stainless Steel Vacuum Flask Market report, including the model files, scenario outputs and recommended implementation timeline, visit the PW Consulting report page or contact our industry team for a confidential briefing and an accelerated deployment package tailored to your firm’s exposure.
For detailed analysis of this topic, please visit the official page: Worldwide Stainless Steel Vacuum Flask Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide FPD Lithography Systems Market Valued at USD 4,280.0 Million in 2025, Set to Reach USD 6,313.3 Million by 2032 at a 5.71% CAGR
By pmarketresearch, 2026-08-18
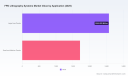
Worldwide FPD Lithography Systems Market: Strategic Outlook for 2026 Decisions
PW Consulting’s latest market study on Worldwide FPD (Flat Panel Display) Lithography Systems synthesizes empirical market trajectories, competitive signals and regulatory vectors to equip C-suite leaders and strategic investors as they set priorities for 2026. Built on a base year of 2025 with a historical window covering 2020–2025 and a forward forecast to 2032, the report quantifies the market and—just as importantly—translates change drivers into executable choices for procurement, partnerships, R&D and M&A. The top-line: the global market expands from an estimated USD 4,280.0 Million in 2025 to an expected USD 6,313.3 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.71% over the forecast period.
Space Chamber Market
Why this report matters for 2026 strategy
-
Timing decisions against a shifting investment cycle: Our analysis identifies a temporary industry pullback in 2026 as major panel manufacturers reassess capital deployments in light of recent tariff and trade-policy shifts. Firms that defer or accelerate purchases without scenario analysis risk either underutilized assets or lost time-to-market.
Worldwide Web Application Firewall (WAF) Software Market -
Regulation and compliance are now strategic levers: Cross-border export controls and chemical compliance frameworks are altering permissible buyer-supplier configurations and product specifications. Our regulatory overlay quantifies exposure to recent export-control expansions and ongoing EU chemicals regimes, enabling legal-informed procurement strategies.
Load Bank Rental for Data Centers Market -
Market concentration shapes negotiating power: The FPD lithography market demonstrates very high concentration at the vendor tier—our competitive concentration metrics highlight an industry where the top three suppliers command the vast majority of revenues. This structural reality changes counterparty behaviours, lead times, service economics and the shape of potential alliances.
Report highlights — what executives will find inside
-
Integrated market-sizing and trajectory modelling: We provide a reconciled historical series (2020–2025) and a granular forecasting engine for 2026–2032. The model embeds macro demand drivers, technology substitution effects and a supply-side capacity build, delivering scenario outputs aligned to strategic decision gates.
-
Scenario-based investment playbooks: Four investment scenarios—Consolidation, Acceleration, Wait-and-See and Regionalization—translate macro foresight into specific procurement and CAPEX timing recommendations. Each playbook includes risk-adjusted NPV sensitivity and break-even timing for major platform classes.
-
Technology and product roadmaps: We map technological inflection points (light sources, multi-lens optics, overlay precision) and their expected impact on yield, throughput and cost per panel. This section supports Make vs Buy debates and R&D prioritization.
-
Supply chain and localization diagnostic: The report contains supplier dependency matrices, single-source exposure heatmaps and practical mitigations—including contract clauses, strategic stocking, and dual-sourcing templates—tailored for 2026 procurement cycles.
-
Commercial and go-to-market playbook: For equipment vendors, we offer differentiated GTM options by customer archetype (leading integrators, high-mix panelmakers, and emerging local champions), supported by pricing levers and service-model optimization to defend margin in a concentrated industry.
-
M&A and partnership screening: The study identifies target profiles and valuation frameworks for bolt-on acquisitions, joint development projects and manufacturing partnerships—critical when incumbents look to expand adjacent capabilities or secure domestic supply in response to trade restrictions.
-
Regulatory compliance toolkit: Practical checklists, certification paths and compliance-cost scenarios are provided so procurement teams and legal counsel can quickly quantify the implications of export controls and hazardous-chemical restrictions on planned purchases.
Competitive landscape — interpreting the signals
The market’s oligopolistic structure concentrates strategic focus on a small number of vendors and a rising cohort of domestic challengers. PW Consulting’s competitive analysis highlights three archetypal players shaping 2026 decision contexts:
-
Nikon Corporation (Tokyo, Japan): A technology leader in multi-lens FPD lithography, Nikon’s recent product activity signals a push to optimize power consumption and high-definition yields. Notably, Nikon announced order acceptance for Gen 8 systems equipped with UV-LED sources in late 2025 and is positioning shipments in early 2026. Nikon’s cross-application capability—translating multi-lens expertise into back-end semiconductor patterned tools—adds strategic optionality for buyers seeking multi-purpose platforms.
-
Canon Inc. (Tokyo, Japan): Canon’s mirror-projection platforms remain a mainstay for array and color-filter processes. Recent product releases demonstrate an emphasis on overlay accuracy and throughput for mid-size automotive and smartphone panel production. Canon’s established aftermarket and service footprint make it a partner of choice for clients prioritizing lifecycle uptime.
-
Shanghai Micro Electronics Equipment Co., Ltd. (SMEE) (Shanghai, China): As domestic industrial strategies intensify, SMEE represents an emergent onshore supplier option. Buyers weighing localization and trade-risk mitigation should evaluate trade-offs across performance, lead times and compliance certifications when considering domestic alternatives.
While these firms’ product announcements and launch timelines are shaping 2026 procurement calendars, buyers must weigh product performance against availability constraints and regulatory permissibility. PW Consulting’s vendor-performance matrices and supplier risk scores are built precisely to support that evaluation process.
Regulatory and geopolitical dynamics affecting 2026
-
Expanded export controls: U.S. export regulations issued in late 2024 broadened controls on advanced lithography components and certain DUV and packaging tools. Aligned policies from other technology-exporting governments have created an uneven ability to move equipment and components across borders—this affects which suppliers can serve which customers in 2026, and at what cadence.
-
Japan’s export policy alignment: Japanese export controls have tightened in step with allied policies, introducing additional procedural requirements for specific categories of lithography hardware and subsystems.
-
Chemicals and environmental compliance: EU-level chemical frameworks continue to constrain material choices for certain process chemistries, raising compliance costs and sometimes forcing design or consumable changes that affect operating expenditure models.
-
Policy-driven investment pauses: Public commentary from major vendors and public filings indicate a near-term investment appraisal by panel manufacturers—this temporary contraction in 2026 demand creates a window for re-negotiating procurement terms and for opportunistic strategic positioning.
Strategic implications and actionable recommendations for 2026
-
Adopt a dual-track procurement strategy: Prepare a primary procurement timeline aligned to your technology roadmap but maintain a contingency queue with alternative suppliers or deferred delivery options. Use contractual instruments that convert cancelled firm orders into priority scheduling once demand recovers.
-
Quantify regulatory exposure up-front: Map each planned purchase against export-control matrices and chemicals compliance checklists to avoid costly retrofits or shipment denials. Incorporate regulatory clause templates into supplier contracts to share compliance risk.
-
Pursue strategic co-development where feasible: For OEMs and panelmakers seeking differentiation, partnering with suppliers on light-source upgrades or overlay enhancements can accelerate access to performance gains while improving supply resilience.
-
Leverage the temporary 2026 slowdown: Buyers with secure order books should negotiate extended service packages and supplier-managed spare pools at favorable economics; investors should scan the market for consolidation opportunities when valuations recalibrate.
-
Prioritize lifecycle economics: Move beyond unit prices to holistic cost-of-ownership models that include energy consumption (a growing differentiator), yield impacts and uptime penalties. Our model translates these inputs into comparable TCOs across vendor platforms.
What we withhold publicly — and how to get it
PW Consulting follows a “trailer” approach in this release: we present the analytical framework, market trajectory and strategic implications to support executive decisions, while reserving granular segment-level allocations and proprietary vendor share detail for subscribers. The report contains detailed splits by region, platform type and application, plus transaction-level vendor share tables that underpin the concentration metrics referenced above. These detailed tables and the interactive forecast model are accessible via the report landing page for clients and registrants.
Conclusion — positioning for 2026
FPD lithography systems sit at the intersection of rapid technological evolution, concentrated supplier power and intensifying regulatory oversight. For 2026, the dominant themes are timing, regulatory alignment and resilience. Organizations that deploy scenario-aligned procurement playbooks, couple technology roadmaps with supplier risk mitigation, and use the temporary market recalibration to optimize lifecycle economics will emerge with structural advantage as demand resumes. PW Consulting’s Worldwide FPD Lithography Systems Market report empowers those decisions with validated market sizing (USD 4,280.0 Million in 2025 growing to USD 6,313.3 Million by 2032 at a 5.71% CAGR), concentration analytics, and actionable playbooks—supporting senior leaders as they navigate 2026’s strategic inflection points.
For full access to segmented data, vendor-specific tables, scenario models and the downloadable forecasting workbook, please visit the official report landing page.
For detailed analysis of this topic, please visit the official page: Worldwide FPD Lithography Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Eco-friendly Beneficiation Reagents Market Poised to Expand at a 6.5% CAGR During 2026–2032
By pmarketresearch, 2026-08-18
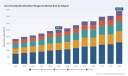
PW Consulting: Strategic Brief — Eco-friendly Beneficiation Reagents Market (2026 Outlook)
PW Consulting today publishes an executive-level briefing that crystallizes the strategic implications of our full market research report on the Eco-friendly Beneficiation Reagents Market. Built for C-suite decision-makers, sustainability leads, and M&A teams, this briefing synthesizes the dynamics that will shape procurement, R&D, and capital allocation choices in 2026 and beyond — while preserving the proprietary, granular intelligence contained in the full report.
Worldwide Big Rig Trucks Market
Executive snapshot: why 2026 matters
The eco-friendly beneficiation reagents market is moving from niche pilot programs to industrial-scale deployment. Our analysis shows the market has expanded materially over the 2020–2025 historical window and enters the 2026–2032 forecast period on a steady growth trajectory. With a compound annual growth rate (CAGR) of 6.5% across the forecast period and market value growth from the low‑single‑billion range in 2020 to a mid‑billion valuation in 2025, the segment is projected to approach the high end of the mid‑single‑billion range by 2032. This growth is sustained by tightening environmental regulation, corporate ESG commitments, and commercially viable bio-based chemistries that reduce aquatic toxicity and lifecycle impacts.
Corded Electric Chainsaws Market
What the full report delivers — practical intelligence for decision makers
- Market sizing and scenario modelling (base year 2025; forecast 2026–2032) with upside and downside scenarios tied to regulatory timelines and feedstock availability.
- A decision-ready regulatory matrix that maps jurisdictional discharge criteria, expected EHS compliance windows, and procurement risk for operators and reagent suppliers.
- Supplier and product playbooks, including techno‑economic assessments, dose-rate benchmarking, and sustainability scoring for formulation classes (collectors, frothers, depressants, pH modifiers).
- Five non-prescriptive, implementable GTM (go-to-market) strategies for incumbent chemical players and new entrants: licensing & co-development, joint piloting with miners, regional distribution partnerships, targeted bolt-on M&A, and customer-financed scale-up models.
- Procurement templates and contracting clauses to de‑risk supply, ensure performance guarantees during trials, and protect environmental liabilities.
- Case studies and pilot metrics demonstrating yield lift, reagent dosing profiles, and tailings‑water chemistry outcomes across representative ore types.
- Feedstock sourcing playbook for bio‑based inputs (lignin streams, fatty acids, sophorolipids), including upstream supplier diligence and processing constraints that affect reagent cost and supply security.
Market structure and competitive tension
The eco-friendly reagents market is neither a classic oligopoly nor a fully fragmented cottage industry. Concentration metrics indicate a market where leading chemical manufacturers hold meaningful influence but do not command majority control: the top three firms account for just over 30% of market activity, and the top five do not exceed half of the market. This mix produces robust competitive tension: global incumbents leverage breadth and distribution; specialized challengers advance differentiated low‑toxicity chemistries and rapid piloting.
Electromagnetic and Optical Navigation System Market
Strategically, this structure creates three viable routes for buyers and investors in 2026:
- Partner with incumbents that can scale production, navigate regulatory approvals, and offer integrated supply chain solutions.
- Pilot with specialized innovators to capture material downstream benefits in recovery and lifecycle impact, while managing scale-up and supply risk.
- Pursue selective M&A to acquire unique, validated chemistries or feedstock supply chains (e.g., lignin processors, biosurfactant producers) that accelerate time to market.
Competitive landscape — positioning of core players
Our report profiles industry leaders and disruptive specialists to show how product portfolios, R&D pipelines, and commercialization models map to customer needs. Key observations:
- Nouryon (Amsterdam) positions sustainability as a product development axis, progressively removing legacy ingredients and advancing lower‑impact flotation formulations with strong industrial scaling capability.
- Clariant (Muttenz) leverages targeted collector and frother platforms to address coarse‑particle flotation and higher‑energy ores, actively showcasing energy‑efficiency gains at industry forums.
- Syensqo (formerly Solvay, Brussels) combines legacy flotation chemistry know‑how with repositioned formulations targeted at base and precious metals, promoting reduced environmental profiles versus traditional xanthates.
- BASF (Ludwigshafen) focuses on reduced dose rates and improved safety (GHS) profiles, seeking to substitute or complement established reagents in phosphate and industrial mineral flowsheets.
- Arkema / ArrMaz (Colombes) and other specialty players target select minerals (phosphate, silica, glass sand) with customized depressant and collector systems emphasizing selectivity and recovery.
- Regional and technology challengers (e.g., CN‑free cyanide alternatives from Yantai, biosurfactant specialists like Locus Mining Solutions in the U.S., and several China‑based formulators) are moving from lab validation into field trials, offering alternatives to legacy toxic chemistries in precious metals and low‑grade tailings contexts.
These profiles in the full report include vendor scorecards that evaluate technical maturity, scale capability, environmental profile, and commercial terms — essential inputs for procurement and M&A diligence.
Regulatory & raw material drivers: vectors of disruption
Two systemic forces are accelerating adoption and reshaping vendor economics:
- Regulation and ESG mandates. Tighter discharge limits, chemical safety frameworks in major jurisdictions (including recent EU activity), and corporate net‑zero/value‑chain commitments are shortening the runway for legacy, high‑toxicity chemistries. Firms that proactively align product dossiers to regulatory expectations reduce time‑to‑adoption and procurement friction.
- Feedstock innovation. Lignin‑based collectors and fatty‑acid (e.g., TOFA) derivatives, plus renewable biosurfactants (sophorolipids), are emerging as feedstocks that deliver high "green" classification scores — combining biodegradability, renewable origin, and safer toxicological profiles. However, commercial-scale feedstock supply chains require upstream coordination (pulp/paper, biodiesel, forestry residues), which we map in the report.
Recent developments underscore these dynamics: Clariant showcased energy‑efficient coarse flotation reagents at a major industry conference; BASF launched a high‑performance industrial minerals flotation reagent aligned to sustainability objectives; and an academic‑industry review introduced a taxonomy for green flotation reagents that helps standardize procurement scoring. Together, these events signal accelerating technology maturation and market readiness.
Risk framework and deployment playbook for 2026
Adopting eco‑friendly reagents at scale is not a simple substitution — it requires an integrated program that addresses technical, commercial, and regulatory risk. The full report provides a four‑layer risk framework and an associated deployment playbook that includes:
- Technical gate criteria: representative bench and pilot metrics (reagent dose curve, selectivity, recovery delta vs baseline) and decision thresholds for scale‑up.
- Commercial safeguards: performance‑linked contracts, staged purchasing, and inventory buffers for new feedstock supply lines.
- Regulatory contingency planning: submission templates, ecotoxicity testing pathways, and timelines aligned with expected permitting windows.
- Stakeholder engagement tactics: community communications templates, third‑party verification options, and sustainability reporting alignment.
Investment and M&A implications
For corporate development and private equity teams, the landscape presents three attractive strategies that we quantify and stress‑test in the report (summary only here): 1) bolt‑on acquisitions to secure unique bio‑feedstock supply; 2) minority growth investments into scale‑ready reagent innovators with locked‑in pilot agreements; and 3) vertical deals that integrate reagent manufacture with water‑treatment services to realize lifecycle value. The market concentration metrics point to continued room for consolidators that can combine technical IP with distribution reach.
How to use this briefing in 2026 planning cycles
- Procurement heads: use the supplier scorecards and contracting templates to run staged trials this year and negotiate performance‑linked pricing for 2027 rollouts.
- R&D chiefs: prioritize partnerships with feedstock suppliers (lignin processors, biosurfactant fermenters) and deploy techno‑economic pilots that track both recovery and life cycle carbon impact.
- Investors and corporate development: target assets that solve feedstock scalability or offer validated field performance against sulfide and oxide ores to minimize technical risk.
Next steps and access to the full report
This briefing deliberately highlights strategic takeaways while omitting the granular segmentation and proprietary vendor scoring that support transaction‑level decisions. The full PW Consulting report contains the detailed regional and application segmentation, supplier scorecards, scenario financials, and implementation toolkits you need to execute in 2026. To access the complete analysis, model files, and workshop options for executive teams, please visit our report page or contact PW Consulting to schedule a tailored briefing session.
PW Consulting is prepared to support executive workshops, pilot selection and oversight, procurement negotiations, and M&A diligence — helping clients convert the macro momentum behind eco‑friendly beneficiation reagents into measurable operational and sustainability gains.
For detailed analysis of this topic, please visit the official page: Eco-friendly Beneficiation Reagents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Main-Chain Liquid Crystalline Polymer Market to Reach USD 2.42 Billion by 2032, Growing at a 7.42% CAGR
By pmarketresearch, 2026-08-18
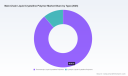
Main-Chain Liquid Crystalline Polymer Market: Strategic Imperatives for 2026 Decision‑Makers
Executive snapshot
The main‑chain liquid crystalline polymer (LCP) market is moving from niche high‑performance applications into a phase of broad strategic importance for electronics, mobility and industrial OEMs. Our market model shows the global market expanding from approximately 1,024 million USD in 2020 to 1,466 million USD in 2025, and—under our central scenario—reaching roughly 2,420 million USD by 2032. That trajectory represents a sustained compound annual growth profile (CAGR) of about 7.42% through the forecast window. Concentration metrics also signal a market where scale and technical differentiation matter: the top three suppliers control a material majority of market share, and the top five approach an overwhelming near‑80% share. For 2026 planning cycles, these dynamics create a narrow window to align sourcing, product strategy and investment timing to avoid being locked out of critical supply and qualification pathways.
Ultrasonic Box Nailer Market
Why 2026 is a pivotal year
- Qualification inflection: OEMs in electronics, automotive electrification and aerospace are tightening qualification corridors for polymer families. The combination of longer testing cycles (driven by regulatory scrutiny) and demand pull from miniaturization and higher operating temperatures means manufacturers must commit to supplier roadmaps earlier to secure next‑generation components.
- Supply chain squeeze: Specialty monomers and feedstock constraints have become a recurrent theme. Limited global supply of purified monomers and batch polymerization characteristics create price volatility and lead times that can materially affect project economics if not hedged through contracts or strategic stockpiles.
- Premium positioning and cost‑to‑serve: Main‑chain LCPs trade at a structural premium—roughly on the order of double high‑temperature nylons—reflecting complex production routes and specialty inputs. That pricing dynamic has implications for value capture, contract negotiation and the economics of substitution versus redesign.
- Regulatory and sustainability acceleration: Updated regulatory frameworks in major markets are extending qualification and disclosure requirements for novel polymer grades. Parallel policy drivers are pushing for traceability, safer chemistries and certified green feedstocks, shifting supplier selection criteria beyond price and into lifecycle performance.
What PW Consulting’s Main‑Chain LCP report delivers (practical, action‑oriented components)
This is not an academic exercise—our report is built to be operational in 2026 decision cycles. Highlights of the practical deliverables include:
Alloy Steel Chains Market
- Robust market model and scenario suite: A multi‑scenario demand engine covering technology adoption curves, end‑market substitution risks, and sensitivity to raw‑material shocks; outputs are provided in downloadable, client‑ready workbooks to support internal planning and board materials.
- Forward pricing and margin model: Granular cost‑builds and margin scenarios incorporating specialty monomer availability, energy cost pass‑throughs, and contract structures (spot, index, long‑term), enabling CFOs to stress‑test P&L impacts under multiple supply scenarios.
- Qualification timeline maps: Practical gating criteria and typical timelines for grade qualification across key OEM segments, with recommended accelerants (pilot runs, co‑development agreements, third‑party validation partners) to compress time‑to‑market.
- Supplier and capability matrix: A strategic supplier map that scores companies on production footprint, technical depth, sustainability credentials and capacity flexibility—designed for procurement to prioritize strategic partners and design dual‑sourcing strategies.
- Technology and product roadmap playbooks: Comparative analysis of thermotropic and lyotropic main‑chain approaches, film versus molding applications, and options for hybrid solutions—plus recommended R&D focus areas with potential ROI windows.
- M&A and partnership screens: Target lists and valuation heuristics for acquisition, minority investments and JV structures aligned to accelerate market entry, access to feedstocks, or capability acquisition (e.g., precision molding, films, battery insulation technologies).
- Risk register and mitigation plans: Practical mitigation for raw material volatility, regulatory lag, and reputational risks from chemical policy shifts—complete with recommended contracting clauses and insurance structures.
To preserve the value of proprietary segmentation and the precise forecasts that underpin supplier selection and M&A screens, we intentionally withhold detailed sub‑segment financials in this release. The full report contains those data tables and interactive models for enterprise use.
Oxide Transparent Ceramics Market
Competitive landscape: who matters and why
- Celanese Corporation (Dallas, Texas): Known for branded LCP lines and engineered compounds that balance flow, heat resistance and dimensional stability—a strategic player in high‑volume electronics and connector markets. Recent capacity additions in China reflect a move to secure local supply for 5G and adjacent electronics demand.
- Polyplastics Co., Ltd. (Tokyo): A precision‑molding oriented supplier that has broadened its portfolio with biomass‑balanced variants, signaling near‑term differentiation on sustainability credentials and supply chain traceability.
- Sumitomo Chemical Co., Ltd. (Tokyo): A major incumbent that has used M&A to consolidate capabilities, recently acquiring LCP neat resin assets to strengthen its ICT and mobility offerings—underscoring a strategy of vertical integration into high‑growth end‑markets.
- Toray Industries, Inc. (Tokyo): A focus on films and high‑frequency applications gives it an edge in advanced electronics and RF components, an area that will be critical as device speeds and thermal loads increase.
- Solvay S.A. (Syensqo) (Brussels): Offers high‑heat and flame‑retardant grades targeting EV battery insulation and industrial applications—an example of product differentiation to address emerging electrification needs.
- Specialist producers (e.g., Ueno Fine Chemicals, Kuraray): Niche capabilities in high‑performance engineering plastics, films and fibers that serve specialized component makers and offer potential acquisition or partnership targets for scaling OEMs.
Recent strategic moves—capacity expansion in China by a global supplier, a biomass‑balanced product launch from a Japan‑based specialist, and a targeted acquisition to consolidate resin assets—illustrate three clear competitive playbooks: scale via capacity, differentiate via sustainability, and consolidate via inorganic growth. For buyers and investors, understanding which supplier follows which playbook is essential for alignment on risk and long‑term support.
Supply chain and raw‑material dynamics
- Monomer availability: Purified terephthalic acid derivatives and specialty hydroxybenzoates are often produced by a narrow set of chemical manufacturers. Disruptions, capacity constraints or quality variability can disrupt full value chains; securing long‑dated offtake or strategic stock positions is therefore a pragmatic step.
- Pricing mechanics: Batch polymerization, specialized purification steps and limited producer competition result in a structurally higher cost basis—suppliers generally command a premium versus commodity high‑temperature polymers. Buyers must model premium capture and the elasticity of demand based on substitution and redesign costs.
- Options to manage risk: Near‑term levers include long‑term supply agreements, collaborative R&D to enable alternative monomer routes, and localized inventory strategies. Longer‑term levers include backward integration, joint ventures with monomer producers, or development of robust recycling loops to offset virgin feedstock exposure.
Regulation, sustainability and the qualification curve
- Regulatory tightening: Recent updates to U.S. TSCA review rules and ongoing EU REACH workstreams increase testing and disclosure obligations for novel grades, extending qualification timelines and raising the upfront compliance cost for new entrants.
- Sustainability as a selection criterion: Policies and buyer preferences increasingly favor traceability and circularity; mass‑balance biomass approaches and certified green feedstocks are emerging as commercially viable differentiators rather than peripheral marketing claims.
- Implication for product strategy: Suppliers that can demonstrate verified feedstock claims, reduced lifecycle impacts, and transparent supply chains will command preferential qualification opportunities with sustainability‑focused OEMs.
A pragmatic decision framework for 2026
2026 should be treated as a decision momentum year. The following prioritized activities will deliver asymmetric value:
- Near term (0–12 months): Lock preferred supply via hybrid contracts (mix of long‑term and flexible volumes), accelerate grade qualification with co‑development partners, and pilot biomass‑balanced or traceable feedstock pathways to signal compliance readiness to customers and regulators.
- Medium term (12–36 months): Execute capacity tie‑ups or JV structures where scale is needed; selectively pursue M&A to acquire missing capabilities (e.g., films, precision molding); and implement pricing strategies that capture structural premium without compromising adoption.
- Long term (>36 months): Invest in circularity (recycling, monomer recovery) and R&D into alternative monomer chemistries that reduce supply dependence and enable new price points. Build multi‑tier supplier ecosystems to mitigate single‑source risks.
How PW Consulting helps operationalize the insights
Our Main‑Chain LCP market study is designed to convert market intelligence into executable moves for procurement, product strategy, corporate development and R&D. The report packages include interactive models, supplier scorecards, qualification pathway templates, CapEx ROI tools and an M&A target shortlist tailored to specific corporate profiles (e.g., OEM, compounder, monomer producer). For procurement teams, we provide negotiation playbooks and contract clauses; for product teams, we offer technical readiness matrices and pilot deployment plans.
To preserve the commercial value of the dataset and to ensure aligned use across enterprise stakeholders, this announcement intentionally refrains from publishing the detailed segment‑level financial tables and regional/application splits included in the full study. If your 2026 strategy depends on precise segment forecasts, supplier share scenarios or tailored M&A screening, the full report and accompanying client workbooks provide those deliverables with licenseable access.
Final takeaways
- The main‑chain LCP market is entering a structurally attractive phase with sustained growth and concentrated supplier power; strategic moves made in 2026 will determine supplier relationships, margin capture and product roadmaps for the rest of the decade.
- Successful players will combine tactical procurement (to manage supply and price exposure), targeted investments (to secure capacity or capability), and sustainability‑driven differentiation (to meet regulatory and customer demands).
- PW Consulting’s study translates these dynamics into actionable plans, models and tools that align board‑level strategy with plant‑floor execution—without compromising the proprietary segmentation and datasets that drive competitive advantage.
For detailed analysis of this topic, please visit the official page: Main-Chain Liquid Crystalline Polymer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Diamond Dotted Paper (DDP) Market Poised to Reach USD 683.56 Million by 2032 on a 4.95% CAGR
By pmarketresearch, 2026-08-18
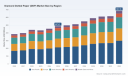
Worldwide Diamond Dotted Paper (DDP) Market: Strategic Imperatives for 2026
PW Consulting’s latest market brief on the Worldwide Diamond Dotted Paper (DDP) market synthesizes five years of historical performance and a forward-looking forecast to 2032, delivering a compact, action-oriented intelligence package for corporate leaders preparing 2026 strategies. Anchored on a formal base year of 2025 and historical coverage from 2020–2025, our analysis shows a market on a steady growth trajectory with a compound annual growth rate (CAGR) of 4.95% and a projected market size moving from approximately USD 487 million in 2025 to an expected USD 684 million by 2032. This release is designed as a strategic “trailer”: it demonstrates analytic rigor and practical depth while directing practitioners to the full report for the granular data that underpins board-level decisions.
Worldwide Air Vent Valves Market
Why DDP Matters to Energy and Electrical Equipment Leaders in 2026
Diamond Dotted Paper is a core insulation component for transformer manufacturing and related electrical equipment. Recent shifts in transformer design philosophies, tighter environmental compliance expectations, and the global drive for grid resilience have collectively elevated the material’s strategic importance. For 2026 planning cycles, three macro themes should shape corporate choices:
Worldwide E-Filing Platforms Market
- Resilient supply strategy: raw-material sourcing and supplier diversification to protect production continuity;
- Material and process compliance: adoption of PFAS-free, high-polymerization base papers and IEC-conformant practices to reduce lifecycle risk;
- Product differentiation: leveraging DDP formulation and quality (e.g., resin distribution, DP levels, tan delta) as a competitive lever in transformer reliability and service life.
What the Report Contains — Practical, Procurement-to-Product Intelligence
The PW Consulting DDP Market report is purposely structured for executives and operational leaders who must translate market intelligence into near-term decisions. Key deliverables include:
Inventory Optimization ERP Software Market
- Market sizing and forecast model (2020–2032) with scenario sensitivity for demand shocks, material inflation, and electric infrastructure investment rates;
- Supply-chain risk matrix that maps single-source exposure, lead-time variability, and logistics hotspots for critical raw materials (electrical-grade Kraft paper, modified epoxy resins);
- Supplier benchmarking toolkit that combines capability scorecards, quality attributes (e.g., degree of polymerization, tan delta, impregnation performance), and commercial terms to accelerate sourcing decisions;
- Regulatory and standards playbook focused on IEC compliance, environmental material requirements, and test protocols critical for qualification cycles;
- Commercial scenario playbooks (pricing, contract structuring, buy-and-hold, JIT strategies) and a practical roll-out timeline for product line qualification and supplier audits;
- Financial decision tools: TCO models, ROI calculators for internal qualification vs. outsourcing, and M&A screening filters tuned to the DDP ecosystem.
These modules are delivered with templates and checklists designed to be used in procurement RFIs/RFPs, innovation roadmaps, and M&A diligence — not just as theoretical insight but as immediately actionable assets for 2026 implementation.
Competitive Landscape: Who Moves the Market and Where Value Is Created
The DDP market displays a moderate degree of concentration. Our analysis indicates the top three suppliers account for a meaningful share of global capacity, and the top five players collectively hold a majority share — a structure that creates both bargaining power for large buyers and consolidation opportunities for strategic acquirers. Key incumbents profiled in the report include:
- Hitachi Energy (Switzerland): recognized for engineered DDP solutions tailored to oil-filled distribution and foil-wound transformers, offering a range of thicknesses and roll widths for coil-strengthening and short-circuit resistance applications.
- delfortgroup AG (Austria): a premium-positioned supplier emphasizing very high degree-of-polymerization base papers, low dielectric loss characteristics, and PFAS-free formulations targeted at lifecycle extension.
- Weidmann Electrical Technology (Switzerland): known for precise resin-dot patterning and product performance that balances mechanical reinforcement with impregnation behavior and partial discharge performance.
- Chinese manufacturers such as ZTelec Group, Chengrui Insulation Material, and Hechin Insulation: cost-competitive producers with vertically integrated capabilities in Kraft base paper and resin patterning, increasingly visible in global commercial engagements and technical dialogue with Western buyers.
Each category of supplier—multinational engineering firms, European premium specialty paper producers, and Chinese-scale manufacturers—brings different strategic trade-offs in quality, compliance posture, lead time, and price. The report’s supplier matrix aligns those trade-offs with procurement objectives, qualification timelines, and risk tolerances to guide partner selection in 2026.
Recent Developments That Shape 2026 Execution
We track market signals that merit immediate attention on your roadmap:
- Standards and guidance: leading manufacturers have reinforced IEC-oriented production practices and published product guides that codify resin distribution and impregnation protocols — accelerating buyer expectations for traceable, testable inputs.
- Environmental positioning: premium suppliers are promoting PFAS-free DDP formulations as a differentiator, a trend that is likely to pressure procurement specifications and compliance checks in developed markets.
- Customer intimacy and qualification cycles: supplier-customer factory visits and technical exchanges are becoming more frequent, signaling that qualification decisions are increasingly informed by direct technical validation rather than price alone.
These developments shorten the feedback loop between R&D and procurement and increase the premium on early technical engagement.
Strategic Actions for 2026 — A Recommended Roadmap
We recommend a sequenced approach for organizations that want to convert market insight into competitive advantage in 2026:
- Immediate (0–6 months): Update procurement specifications to require IEC conformity evidence, PFAS-free certification where relevant, and supplier-provided DP/tan-delta data. Start parallel qualification pilots with one premium and one cost-competitive supplier to compress lead times.
- Near-term (6–18 months): Implement the supplier scorecard from our report to re-balance sourcing across tiers, lock multi-year agreements with price indexation, and secure safety-stock parity at strategic nodes in the supply chain.
- Medium-term (18–36 months): Invest in co-development partnerships for next-generation impregnation-resin patterns and pilot programs that quantify lifecycle gains attributable to DDP quality improvements; evaluate bolt-on M&A targets that close capability or geographic gaps.
Risk and Mitigation — What to Watch in 2026
Key risks that materialize in procurement and product planning include raw-material volatility (Kraft pulp, specialty resins), regulatory shifts on chemical constituents, and capacity imbalances in specific geographic clusters. Mitigation levers include dual-sourcing strategies, contractual resilience (long-term offtakes with dedicated capacity), and accelerated qualification protocols that reduce time-to-production for alternative suppliers. The PW report includes a prioritized set of mitigation measures matched to impact and execution complexity.
How PW Consulting’s Analysis Adds Value for Decision-Makers
Why rely on this market brief as you set budgets and initiatives for 2026? Three practical advantages:
- Decision-ready modeling: Our topline forecast (base year 2025, 2026–2032 outlook) is structured to be dropped into capital planning and procurement budgets without rework;
- Action tools: templates, supplier scorecards, and RFP language that accelerate procurement cycles and reduce legal/technical back-and-forth;
- Competitive signals: annotated company dossiers and recent-development timelines that help prioritize supplier engagements and M&A screening for rapid execution.
Next Steps: Where to Get the Full Intelligence
This release is a prelude to the full PW Consulting DDP Market Report, which contains the granular segmentation, regional dynamics, application-level demand drivers, and a complete supplier intelligence database that many teams will need to finalize 2026 capital and sourcing plans. To preserve competitive advantage for our subscribers and to ensure rigorous data governance, the report’s detailed segment tables and company-level revenue splits are available on the report portal. Access to the full dataset includes working models and editable templates for immediate use in board decks and procurement negotiations.
For procurement heads, product managers, corporate development teams, and investor relations officers preparing 2026 strategies, PW Consulting’s DDP analysis is engineered to be both a strategic compass and an operational toolkit. The market is growing steadily; the choices you make in supplier selection, specification tightening, and qualification execution in 2026 will materially affect product reliability, total cost of ownership, and competitive positioning across the next investment cycle.
Contact PW Consulting to request the comprehensive report package, secure a briefing with our senior industry analysts, or license the forecast model for internal use. Our team can also run a tailored supplier risk assessment workshop to help you convert insight into executable contracts and product qualification timelines for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Diamond Dotted Paper (DDP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Hot Tapping Machines Market Set to Grow at a 4.7% CAGR Through 2032
By pmarketresearch, 2026-08-18
Worldwide Hot Tapping Machines Market — Strategic Outlook 2026: A PW Consulting Intelligence Preview
PW Consulting today publishes an executive preview of our full "Worldwide Hot Tapping Machines Market" study (base year 2025, forecast 2026–2032). The global market reached approximately USD 680 Million in 2025 and, under a base-case growth trajectory, is projected to expand at a compound annual growth rate (CAGR) of roughly 4.7% through 2032. By 2032 the market is expected to be in the high hundreds of millions (USD), reflecting steady demand driven by pipeline integrity programs, water infrastructure rehabilitation, and industrial in-service interventions.
HBM Controller IP Market
Why this intelligence matters for 2026 decision-making
-
Operational resilience is now a board-level priority. Hot tapping remains one of the few reliable means to perform branch connections, repairs and interventions without service interruption—making procurement, supplier selection and deployment timing material to uptime and commercial continuity.
International Casualty Market -
Investment and procurement windows are compressing. With a predictable mid-single-digit CAGR and a shifting mix of project types, organizations that align capex and strategic sourcing with our scenario models will reduce acquisition costs, shorten lead times and improve fleet utilization.
Research Inverted Microscopes Market -
Regulatory and insurer scrutiny is intensifying. Standards and best practices put compliance and traceability at the front of RFPs; failure to demonstrate certified materials and documented testing can materially increase project costs and delay approvals.
-
M&A and consolidation optics are clear: concentration metrics in our study show a market where a handful of incumbent suppliers capture a meaningful share—creating both scale advantages for established players and niche opportunities for specialist providers.
What the full report delivers — practical, transaction-ready tools
-
Market sizing with transparent methodology: a reconciled top-down and bottom-up valuation for 2020–2025 and forward-looking scenarios for 2026–2032, enabling investors to stress-test revenue and margin outcomes under multiple demand and price environments.
-
Buyer’s playbooks and tender templates: procurement-ready scoring matrices that factor engineering capability, certification, warranty terms, spares availability and lead-time risk.
-
Supplier capability heatmaps and scorecards: comparative assessments that benchmark technical breadth, manufacturing depth, subsea and sour-service readiness, aftermarket coverage and geographical service footprints.
-
Operational checklists and field guides: inspection protocols, pre-deployment validation tests and maintenance routines tailored to high-pressure, low-pressure and municipal deployments.
-
Financial models and ROI calculators: downloadable spreadsheets for capex/opex trade-offs, shared-equipment pool economics, lifecycle cost of ownership and aftermarket revenue scenarios.
-
M&A diligence templates: a focused due-diligence pack that highlights contract liabilities, backlog quality, supplier concentration exposure and integration flags specific to hot tapping businesses.
-
Regulatory matrix and materials compliance map: line-by-line guidance showing how applicable codes and standards (including pipeline and pressure-equipment references) translate into procurement requirements and test plans.
Strategic implications and recommended plays for 2026
-
For OEMs: prioritize certification and traceability. The intersection of regulatory expectations and buyer scrutiny makes ASME/BPVC-equivalent certifications and NACE-compliant materials a non-negotiable. OEMs that invest in documented materials traceability, cryogenic/impact testing and sour-service capability will secure premium contracts and reduce warranty exposure.
-
For operators and EPCs: shift from transactional purchasing to asset-pool strategies. Given predictable demand growth, a shared-equipment model (joint ownership, regional depots, or managed service contracts) can materially reduce unit costs and idle time.
-
For aftermarket and service providers: develop bundled offerings. Combining hot tapping with line stopping, in-service welding, diagnostics and digital monitoring creates sticky revenue streams and increases lifetime customer value.
-
For investors and acquirers: screen for engineering differentiation and manufacturing control. Market concentration indicates room for bolt-on consolidation; target companies with proprietary tooling, strong in-house machining and repeatable aftermarket revenue.
Competitive landscape — what leading players signal about market direction
-
T.D. Williamson (TDW) — a broad catalog and global service network. TDW’s portfolio across large-diameter, onshore and offshore taps demonstrates the value of product breadth combined with field service capability for large operators.
-
STATS Group — specialization and in-house control. STATS’ proprietary high-pressure SureTap family and its recent manufacturing investment in Aberdeenshire underline a strategic choice: owning critical manufacturing capability to shorten delivery cycles and protect IP.
-
Reed Manufacturing and similarly focused mechanical providers — cost-effective small-diameter solutions. These firms occupy an essential position for lower-pressure civil and utility works where simplicity and reliability trump exotic capability.
-
Mueller Co., Aquatap and municipal-focused suppliers — entrenched water-sector expertise. Long-term relationships and domain knowledge in water-main interventions are strong defensive assets against new entrants.
-
Propipe, TECPESA and custom-engineering firms — high-pressure, high-temperature specialists. Their engineering-first model is attractive for petrochemical and heavy industrial clients who demand bespoke solutions.
-
Accessories and turnkey vendors such as Petersen Products, Enerpac (Mirage), 2LBin and Wheeler-Rex — they complete the ecosystem. Competitive advantage in this segment is driven by distribution reach, spares availability and modularity of systems.
-
Market activity signals: recent capital expenditure announced by a leading specialized manufacturer and industry sessions at the 2026 Pipeline Technology Conference indicate continued focus on manufacturing resilience, field reliability, and cross-disciplinary repair techniques.
Regulatory and materials landscape — compliance as a strategic asset
-
Standards and codes such as API’s hot tapping guidance and widely adopted ASME pipeline/pressure codes remain primary gating factors for field approval. Compliance is not just a checkbox; it materially affects insurability and contractors’ mobilization timelines.
-
Materials requirements matter. The use of pressure-vessel-grade steels, impact-tested components for low-temperature service and resistance to sulphide stress cracking per industry specifications are recurring procurement qualifiers in major tenders.
-
Procurement implication: request documented evidence of testing and third-party certification early in the RFP phase; failure to do so will elongate technical clarifications and increase commercial risk.
How to use this preview: three immediate next steps
-
Run a supplier readiness audit against our procurement checklist. Confirm certifications, spare-parts lead times and on-site commissioning capabilities ahead of project sanctions.
-
Model capex phasing with our mid-case CAGR assumption (4.7%) and test upside/downside scenarios for 24–36 month procurement cycles—this will identify optimal ordering windows and inventory buffers.
-
Engage with targeted OEMs for pilot programs that bundle equipment rental, service contracts and digital monitoring—pilots accelerate validation and reduce time-to-value for operators.
Access the full intelligence
This release intentionally highlights the strategic and operational insights PW Consulting provides while withholding proprietary segment-level splits and supplier scorecards that form the core of our paid study. The full report contains interactive models, vendor-level assessments, region- and application-specific forecasts, and downloadable procurement tools designed for immediate deployment by strategy teams, procurement departments and investors.
To obtain the complete report and the accompanying Excel toolset, contact PW Consulting’s research desk or visit our reports page. Our analysts stand ready to provide tailored briefings and scenario workshops to translate the findings into a 90–180 day action plan for your organization.
PW Consulting — converting market intelligence into executable strategy for the hot tapping ecosystem.
For detailed analysis of this topic, please visit the official page: Worldwide Hot Tapping Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Commercial Submersible Market Poised to Reach USD 513.25 Million by 2032, Growing at an 8.74% CAGR
By pmarketresearch, 2026-08-18
Worldwide Commercial Submersible Market: Strategic Imperatives for 2026 Decision‑Makers
PW Consulting's newest market study on the Worldwide Commercial Submersible Market serves as an operationally focused, strategy‑grade briefing for executives preparing capex decisions, product roadmaps, and M&A/partnership plays in 2026. Built on a 2020–2025 historical baseline and a 2026–2032 forecast horizon, the study synthesizes commercial dynamics, regulatory shifts, cost drivers, and supplier positioning into actionable recommendations — while preserving proprietary segment-level intelligence for subscribers.
Worldwide Cloud Management Platform (CMP) Market
Executive snapshot: What the macro picture means for your 2026 plan
-
Momentum: The commercial submersible market demonstrated consistent recovery and expansion through 2020–2025, rising from a low‑posture base to approximately USD 285.5 Million in 2025. Our forecast models, calibrated to demand drivers and regulatory tailwinds, project continued expansion to a mid‑cycle market of roughly USD 513.3 Million by 2032 at a compound annual growth rate (CAGR) of 8.74% for the 2026–2032 forecast period.
Small Popcorn Machine Market -
Concentration: Market concentration is meaningful — the three largest global suppliers account for roughly 45.5% of industry revenue, while the five largest capture about 62.3%. This creates a competitive landscape where scale, channel depth, and aftermarket capabilities materially differentiate outcomes.
Worldwide Injectable Cement Market -
Strategic timing: 2026 is a pivot year. With infrastructure spending and urbanization accelerating demand for wastewater management, dewatering, and groundwater extraction, buyers will shift procurement logic from capex minimization to lifecycle efficiency and compliance readiness.
Why this report matters to C‑suite and investment committees in 2026
-
Actionable, not academic: The study translates macro growth into decision trees for procurement, product investments, and service monetization. It avoids generic forecasts and instead maps demand scenarios to procurement windows, retrofit cycles, and capital replacement horizons relevant to municipal, commercial, and industrial operators.
-
Regulatory foresight: With energy and efficiency regulation intensifying — including the EU Ecodesign regime's MEI thresholds and U.S. DOE test/procedure emphasis on wire‑to‑water efficiency — our analysis quantifies compliance exposure and phased investment needs by pump class (full methodology included in the report).
-
Cost and supply‑chain sensitivity: We model raw material and manufacturing cost sensitivity, identify key margin pressure points, and outline hedging and sourcing strategies. Manufacturers and buyers alike can use the provided stress tests to evaluate contract pricing and vertical integration tradeoffs.
Market trajectory: evidence and interpretation
The market’s progression from the 2020 baseline into 2025 reflects a combination of deferred municipal upgrades, renewed commercial construction, and early commercialization of higher‑margin product families. Our base‑year calibration at 2025 anchors forward scenarios that show a structurally higher trajectory through 2032 driven by three converging forces: (1) rising infrastructure and urban resilience spending, (2) regulatory tightening on pump efficiency and emissions across major markets, and (3) product innovation enabling longer service intervals and new application niches.
These forces combine to elevate total addressable revenue and shift competitiveness toward firms that can offer not only hardware but predictable lifecycle performance and digital‑enabled service contracts. For buyers, the implication is clear: unit price will increasingly be a secondary metric to lifecycle cost, uptime guarantees, and regulatory proof points.
Key growth drivers and risk vectors
-
Infrastructure and urbanization: Continued public and private infrastructure investment underpins base demand for wastewater and water‑handling pump fleets.
-
Efficiency and regulation: MEI thresholds and DOE test regimes are accelerating replacement cycles for legacy equipment and favoring vendors with validated efficiency claims and certification roadmaps.
-
Materials and input cost volatility: Manufacturers face raw material cycles and capacity constraints. Our scenario work shows how component lead‑times and material price swings alter supplier margins and delivery risk.
-
Product innovation and aftermarket services: Launches of rugged stainless steel ranges, explosion‑proof wastewater lines, and abrasion‑resistant dewatering pumps are expanding addressable applications and enabling value‑added service contracts.
-
Concentration and consolidation: With the top tier controlling the majority of revenue, M&A activity and channel partnerships will be decisive — especially for regional specialists and aftermarket service providers.
Competitive landscape — who matters and why
Our competitor profiles emphasize strategic positioning rather than feature lists. Notable incumbents covered in the study include established global players with differentiated go‑to‑market models:
-
Xylem Inc. — A broad portfolio operator with recognized brand franchises focused on solids‑handling and energy‑efficient designs. Their strength lies in integrated systems and channel reach in municipal and commercial segments.
-
Grundfos — Reputation for reliability and sustainability solutions in building and infrastructure water systems; a leader where energy efficiency and long lifecycle value are procurement priorities.
-
Sulzer and Flowserve — Engineering‑heavy vendors that compete on robustness and application engineering in industrial process and treatment applications.
-
KSB and Franklin Electric — Deliver product breadth for demanding environments, from deep boreholes to abrasive dewatering; recent product introductions show renewed R&D focus on axial‑propeller motors and heavy‑duty assemblies.
-
Tsurumi, Ebara, Weir, and specialist OEMs — Each brings geographic specialization, durability narratives, or slurry/abrasion expertise that matter in specific commercial verticals.
Recent vendor activity underscores the shift toward differentiated hardware and service bundles: notable 2025 developments included rugged stainless ranges and axial‑propeller motor launches, expanded wastewater pump lineups with enhanced solids‑handling, and high‑efficiency explosion‑proof offerings showcased at major trade shows. These moves confirm that manufacturers are prioritizing regulatory compliance, field reliability, and serviceability as pathways to protect and grow share.
What’s inside the PW Consulting report (practical elements)
-
Proprietary demand model: A bottom‑up demand model calibrated across 2020–2025 and stress‑tested for 2026–2032 scenarios. The model converts infrastructure spend, urbanization, and replacement cycles into procurement timing and SKU demand curves.
-
Regulatory and test‑procedure playbook: Plain‑language implications of Ecodesign and DOE regimes, compliance impact by pump family, and certification roadmaps for product managers.
-
Cost and margin simulation: Factory‑gate cost build‑ups, material sensitivity analyses, and recommended supplier contracting strategies to protect margins under commodity swings.
-
Competitive heatmaps: Positioning maps that synthesize scale, service capability, regulatory readiness, and aftermarket potential to identify acquisition and partnership targets.
-
Commercial playbooks: Sales motions, pricing frameworks, and aftermarket monetization templates (service tiers, SLA design, and predictive maintenance economics) that commercial leaders can deploy within 90–180 days.
-
M&A and carve‑out screening: A prioritized list of targets and value drivers with return thresholds and integration risk diagnostics (full target identities and financials are provided to subscribers).
Strategic implications and recommended moves for 2026
-
Manufacturers: Prioritize certified efficiency upgrades and modular service platforms. Use 2026 to build or acquire digital diagnostics and aftermarket capabilities that convert one‑time sales into annuity streams.
-
Buyers/Operators: Shift procurement specifications to lifecycle metrics and require regulatory compliance evidence up front. Negotiate performance‑based contracts to align supplier incentives with uptime and efficiency outcomes.
-
Investors: Seek midsized OEMs with specialized application expertise and recurring service revenue potential. Our valuation scenarios show premium multiple expansion for targets that demonstrate >30% aftermarket revenue growth within three years post‑acquisition.
-
Policy and standards groups: Engage proactively with regulators. Early participation in test‑procedure discussions can shape practical, industry‑aligned compliance pathways that reduce retrofitting risk.
Information governance: what we withheld and why
Consistent with the “trailer” principle, PW Consulting displays analytical depth in the public briefing while reserving granular segment and regional breakdowns for subscribers. This includes detailed segment revenue splits, per‑region demand trajectories, and proprietary SKU‑level forecasts that clients use to calibrate tender responses, negotiate supplier contracts, and validate targets during diligence. The public summary signals opportunity and risk; the full dataset enables executable plans.
How to use this intelligence in practice
-
Integrate the demand model outputs with your procurement calendar to reorder capital projects and prioritize retrofit programs in 2026–2027.
-
Use the regulatory playbook to pre‑qualify product portfolios and avoid post‑procurement compliance costs.
-
Deploy the competitive heatmaps during vendor selection and M&A diligence to rapidly identify strategic fits and white‑space partnerships.
Next steps — accessing the full intelligence
Executives preparing 2026 budgets or evaluating buy/sell decisions should treat this briefing as an operational confidence tool and the full report as the decision‑grade dataset. The comprehensive subscription includes model files, vendor financials, SKU‑level forecasts, and a one‑day client workshop to translate findings into a 90‑day execution roadmap.
PW Consulting is available to present a tailored executive briefing and to provide bespoke scenario runs aligned to your procurement or investment constraints. For details on subscribing to the full Worldwide Commercial Submersible Market report and to schedule a workshop, please visit our report page (full subscription required to access segment‑level datasets and appendices).
In a market moving from replacement cycles to performance‑driven procurement, 2026 will reward organizations that combine technical compliance, aftermarket economics, and supply‑chain resilience. Our study gives leaders the framework and tools to make those judgments with confidence — while our proprietary datasets provide the tactical specificity that turns strategy into measurable returns.
For detailed analysis of this topic, please visit the official page: Worldwide Commercial Submersible Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com